Debt rarely becomes a problem overnight. It creeps up: a new card here, a payment plan there, a loan to cover a gap. By the time it feels heavy, it can be hard to see a way out. Spotting the warning signs early makes everything easier.
1. You only ever pay the minimum
If minimum payments are all you can manage, your balances will barely move. See the minimum payment trap.
2. You use credit for everyday essentials
Putting groceries, fuel or bills on a credit card because your account is empty is a sign that spending is higher than income.
3. You borrow to repay other debts
Using one card to pay another, or a new loan to cover old payments, means the debt is growing even if it feels under control.
4. Your balances aren’t going down
Compare your total debt today with six or twelve months ago. If it’s the same or higher, it’s time to act.
5. You don’t know exactly how much you owe
Avoiding the total is very common — and a sign that debt is causing stress.
6. You’ve missed payments or are getting calls
Late payments, reminder letters and calls from lenders are clear signals to get help early.
7. You have no savings at all
Without any emergency fund, every surprise becomes new debt, keeping you stuck in a cycle.
8. Money is affecting your sleep, health or relationships
Worry, arguments about money or hiding spending from a partner are signs that debt is taking a toll beyond your bank balance.
A simple debt check
Add up all your monthly debt payments (not including your mortgage or rent) and divide by your monthly take-home pay.
- Under 10%: generally manageable. Keep paying it down.
- 10–20%: debt is squeezing your budget. Stop new borrowing and make a plan.
- Over 20%: a danger zone. Act now and consider free debt advice.
These are general rules of thumb, not strict limits, but they give you a useful picture.
What to do next
- Stop borrowing. No new cards, loans or buy-now-pay-later.
- List every debt — balance, interest rate, minimum payment and due date.
- Make a budget so you know exactly what you can afford to pay. Start with how to make your first budget.
- Protect essentials — housing, utilities and food come first.
- Build a small emergency fund so new surprises don’t become new debt.
- Choose a payoff method — snowball or avalanche.
- Talk to your lenders if you can’t keep up — see how to talk to your lender.
- Get free advice from a non-profit debt service if you feel overwhelmed.
You can turn this around
Recognising the signs is the first and hardest step. With a clear list, a realistic budget and one debt at a time, progress comes faster than you’d expect — and every payment is a step towards freedom.
Frequently asked questions
Is all debt bad?
Not necessarily. A mortgage or a reasonable loan for education or a reliable car can make sense if it’s affordable. Problems start when debt is used for everyday spending or payments take up too much of your income.
How quickly can I get out of debt?
It depends on how much you owe, your interest rates and how much extra you can pay each month. Many people are surprised how much faster they progress once they stop borrowing and focus on one debt at a time.
Should I use savings to pay off debt?
Keep a small emergency fund, even while paying off debt. Using every penny of savings can leave you borrowing again when the next surprise arrives.
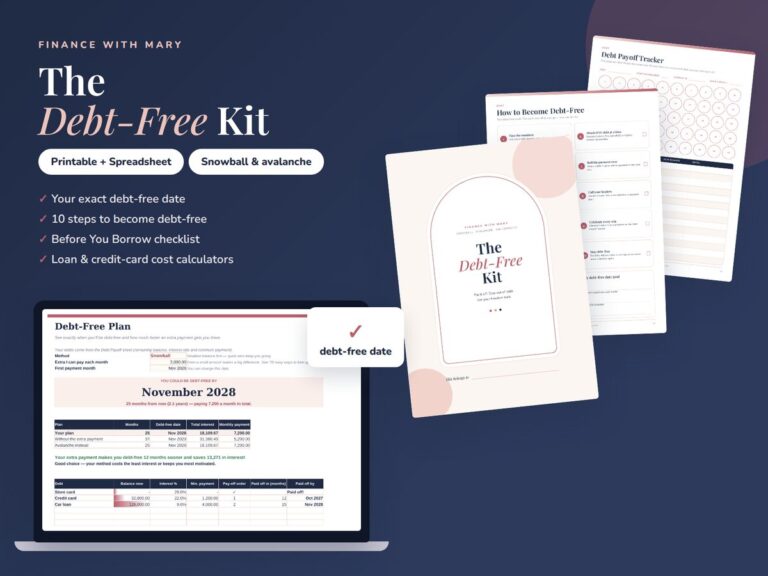
The Debt-Free Kit walks you through these exact steps, with printable trackers and a spreadsheet that shows your debt-free date.
 New
The Debt-Free Kit
Printables + spreadsheet: your debt-free date, a 10-step plan, payoff trackers and a Before You Borrow checklist.
