Should you save or pay off debt? Invest or build an emergency fund? When there are so many things you “should” do with money, it’s easy to feel stuck. A roadmap helps: focus on one step at a time, in a sensible order, and you’ll make steady progress.
Here’s a simple seven-step plan that works for many people. Your situation may be different, so adapt it as needed.
Step 0: Spend less than you earn
Before anything else, make sure more money comes in than goes out. If you’re overspending every month, no other step will work. Start with a simple budget.
Step 1: Build a starter emergency fund
Save one month of essential expenses (or $500–$1,000 to begin). This small cushion stops minor emergencies from becoming new debt. See how to build an emergency fund.
Step 2: Stop borrowing
Commit to no new loans, credit card balances, store credit or buy-now-pay-later. You can’t dig out of a hole while you’re still digging. Use these 10 questions whenever you’re tempted.
Step 3: Pay off all debt except your home
List every debt and pay them off one at a time using the snowball or avalanche method. Put every extra dollar here. This is often the step that changes everything: once your income isn’t going to lenders, saving becomes much easier.
Step 4: Build a full emergency fund
Grow your emergency fund to three to six months of essential expenses (more if your income is irregular). Now you’re protected against bigger shocks like job loss.
Step 5: Save ahead with sinking funds
Set aside a little every month for predictable costs — car, school fees, festivals, holidays, home repairs. Sinking funds mean you’ll never need to borrow for these again.
Step 6: Invest for the long term
With debt gone and savings in place, start investing for retirement and long-term goals. Many people aim for around 15% of income over time. Learn the basics in investing for beginners, and consider independent professional advice.
Step 7: Build wealth and give generously
Pay off your home early if that’s a goal, keep investing and enjoy the freedom you’ve built. This is also the stage where many people choose to give more to family, community and causes they care about.
Does everyone need to follow this order?
No. For example, if your employer matches retirement contributions, it may make sense to contribute enough to get the full match even while paying off debt. And if your debts have very low interest, your priorities might differ. The roadmap is a guide, not a rule.
How to use the roadmap
- Find which step you’re on today.
- Focus your extra money on that one step.
- Celebrate when you move to the next one.
- Review your progress every month.
Find your next step automatically
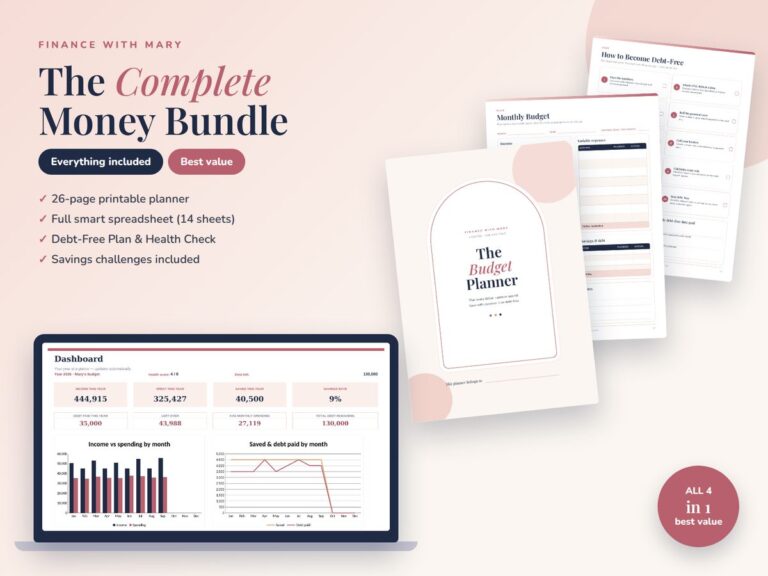
The Smart Budget Spreadsheet includes a Money Health Check that looks at your numbers and tells you which step you’re on and what to do next. The printable planner includes a Money Roadmap page to tick off each step with the date you finish.
 Best value
The Complete Money Bundle
All 4 products in one: 26 printable pages + a 14-sheet smart spreadsheet with a Debt-Free Plan and Money Health Check.
