Your income tells you how much money comes in. Your budget tells you where it goes. But your net worth tells you where you stand overall. It’s one of the most useful numbers to track — and it’s simple to calculate.
What is net worth?
Net worth = what you own (assets) − what you owe (liabilities)
If you own more than you owe, your net worth is positive. If you owe more than you own — common when you’re young, studying or paying off debt — it’s negative. A negative net worth isn’t a failure; it’s a starting point.
Step 1: List your assets
Assets are things you own that have value:
- Cash and current account balances
- Savings accounts and emergency fund
- Investments and retirement or pension accounts
- Property (current market value)
- Vehicles (realistic resale value)
- Other valuable items you could sell
Use realistic values. Your car is worth what someone would pay for it today, not what you paid.
Step 2: List your liabilities
Liabilities are debts you owe:
- Mortgage
- Car loans
- Personal loans
- Credit cards and store cards
- Student loans
- Buy-now-pay-later balances
- Money owed to family or friends
Step 3: Subtract
Example:
- Assets: savings $6,000 + car $8,000 + retirement account $12,000 = $26,000
- Liabilities: car loan $5,000 + credit card $3,000 + student loan $10,000 = $18,000
- Net worth: $26,000 − $18,000 = $8,000
Why track your net worth?
- It shows real progress. Paying off debt and saving both increase it, even if your income doesn’t change.
- It keeps you motivated. Watching the number grow over months and years is powerful.
- It reveals problems. If it’s falling, you can find out why.
How often should you check?
Every three months is plenty for most people. Checking daily can be stressful, especially if you have investments that go up and down. Add it to every third monthly money date.
How to grow your net worth
- Spend less than you earn — the gap is what builds wealth.
- Pay off debt, especially high-interest debt. See snowball vs avalanche.
- Build savings, starting with your emergency fund.
- Invest for the long term once your foundations are in place. Read investing for beginners.
- Avoid buying things on credit that lose value, like new cars and gadgets.
Don’t compare
Your net worth is personal. Comparing with friends or online averages rarely helps. The only comparison that matters is with your own number three months ago.
Frequently asked questions
Is a negative net worth bad?
It’s very common, especially early in your career or when paying off student loans. What matters is that it improves over time.
Should I include my house?
Yes, include its realistic market value as an asset and your mortgage as a liability.
Do I include my car?
Yes, at its realistic resale value. Remember that cars usually lose value over time.
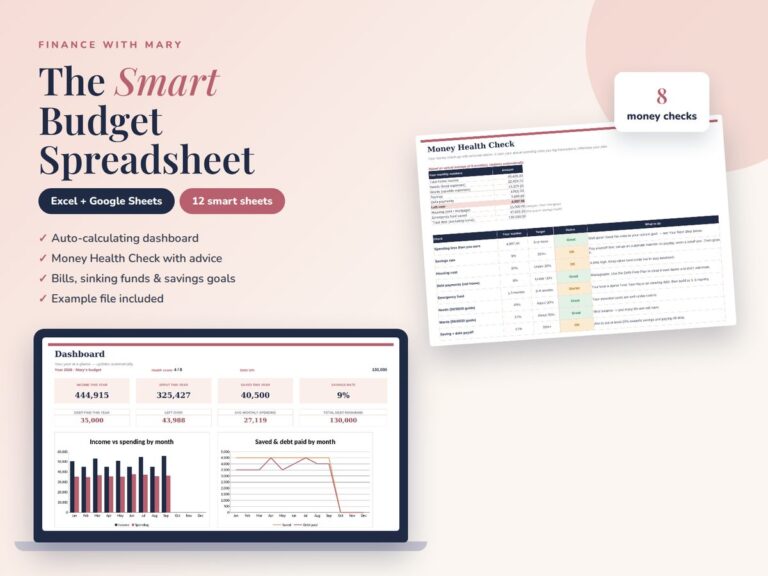
Both our printable planner bundle and the Smart Budget Spreadsheet include a Net Worth Tracker that you update every quarter — the spreadsheet even draws a chart of your progress.
 Most popular
The Smart Budget Spreadsheet
12 smart sheets: dashboard, Money Health Check with personal advice, bills, sinking funds, savings goals and more.
